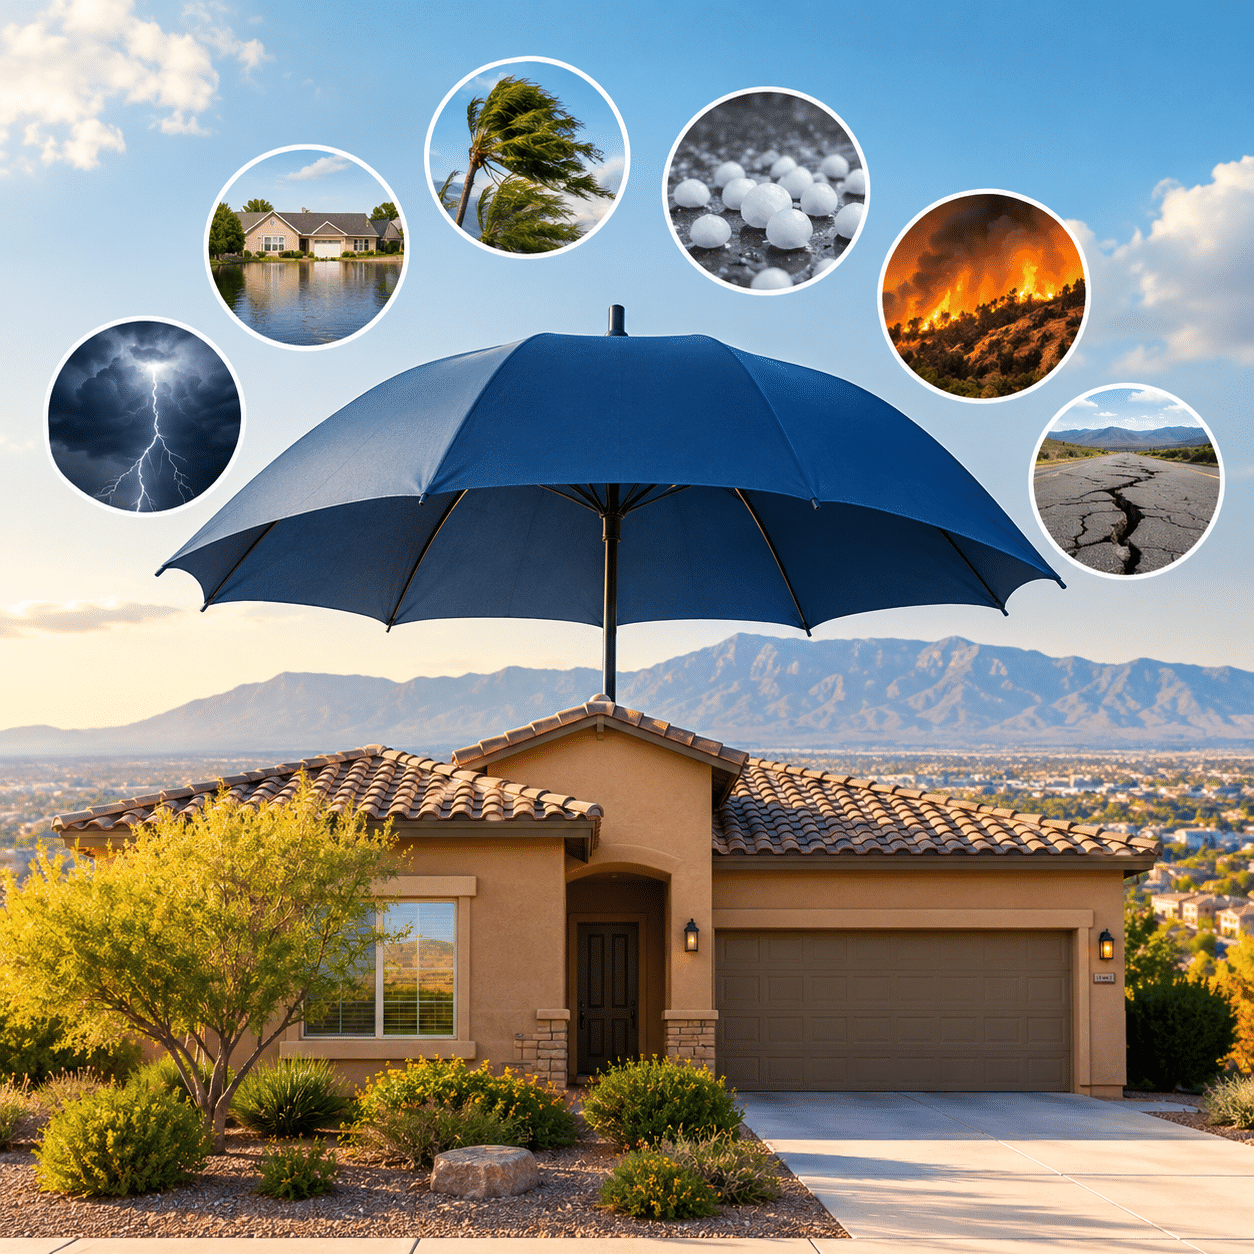
Most homeowners insurance policies provide important protection for your home and belongings, but there are some situations where the coverage people expect to have may be limited or excluded.
That’s why one of the most important things you can do as a homeowner is understand what your policy actually covers before you need to use it.
Here are seven common insurance surprises homeowners may encounter.
1. Flood Damage May Not Be Covered
One of the biggest misconceptions about homeowners insurance is that it automatically covers flooding.
Standard homeowners insurance generally does not cover damage caused by flooding. Flood insurance is typically a separate type of coverage.
And flooding doesn’t only happen in areas near rivers or bodies of water. Heavy rain, rapid snowmelt, drainage issues and other events can contribute to flooding.
If you live in an area where flooding is a possibility, it’s worth understanding your options before a major storm happens.
2. Sewer or Drain Backups May Have Limited Coverage
A backed-up sewer or drain can cause significant damage to flooring, walls, furniture and personal belongings.
However, coverage for sewer and drain backups may not automatically be included in a standard homeowners policy. Some policies offer it as an optional coverage, and limits can vary.
If your home has a basement, older plumbing or other factors that could make a backup especially costly, this is a coverage worth asking about.
3. Your Roof May Not Be Covered for Every Cause of Damage
Homeowners often assume that if something happens to the roof, insurance will pay for the repairs.
The reality can be more complicated.
Coverage can depend on what caused the damage, the age and condition of the roof, your policy language and other factors. Normal wear and tear and maintenance issues are generally not the same as sudden damage from a covered event.
Knowing how your policy handles roof damage can help prevent an unpleasant surprise when you need to file a claim.
4. Earthquake Damage Is Usually a Separate Concern
New Mexico homeowners may not think about earthquakes as often as homeowners in some other parts of the country, but earthquakes can and do happen.
Standard homeowners insurance generally does not cover earthquake damage. Earthquake insurance is typically purchased separately or added through an endorsement, depending on the insurer.
If earthquake protection is something you’re considering, it’s a good idea to discuss the available options with your insurance professional.
5. Home-Based Businesses May Need Additional Coverage
Do you run a business from your home?
Your homeowners policy may provide some limited coverage for business property, but it may not provide everything you need to protect your business equipment, inventory or liability.
If you work from home, run a small business, sell products or keep business equipment at your house, let your insurance agent know.
The right coverage can depend on the type of business you operate and what you keep or do at your home.
6. High-Value Belongings May Have Special Limits
Your homeowners insurance may cover your personal belongings, but certain types of valuable property can have specific limits.
Jewelry, collectibles, firearms, artwork and other high-value items may have coverage limitations depending on your policy.
If you own something that would be difficult or expensive to replace, don’t assume it’s fully covered simply because it’s inside your home.
Ask about the coverage available for those items and whether additional protection may be appropriate.
7. Replacement Cost and What You Paid Aren’t Always the Same Thing
Another common misunderstanding involves the amount it would cost to rebuild your home.
The amount you paid for your house, its current market value and the cost to rebuild it are three different things.
Construction costs, labor, materials and other expenses can change over time. Your dwelling coverage should be based on the estimated cost to rebuild your home according to the terms of your policy, rather than simply its real estate value.
That’s one reason reviewing your coverage periodically can be so important.
The Biggest Insurance Surprise? Not Knowing What’s in Your Policy
Insurance can get complicated quickly, especially when you’re trying to understand exclusions, deductibles, limits and optional coverage.
The good news is that you don’t have to wait until something goes wrong to find out what your policy says.
A quick coverage review can help you understand:
- What your policy covers
- What it excludes
- Where coverage limits apply
- What your deductible is
- Whether your coverage still reflects your current home and belongings
- Whether additional coverage may make sense for your situation
Every policy is different, and coverage depends on the specific terms and conditions of your policy.
If you haven’t looked at your homeowners insurance in a while, this could be a good time to review it.
Don’t wait until you have a claim to discover what your policy says.
Have Questions About Your Coverage?
Your home and your insurance needs can change over time. If you’re not sure what your policy covers, or you’d like to make sure you have the protection you need, give the ABQ Insurance office a call.
We’re happy to review your coverage and provide a quote.
📞 Call our office today to get started.
ABQ – 505-217-2100
Rio Rancho – 505-433-6990