Buying your first home is a big milestone. After years of renting, you’re suddenly responsible for a lot more than remembering to pay the rent on time.
You’re now protecting a home, your belongings, and one of the biggest investments you may ever make.
One of the first things to think about? Homeowners insurance.
Here are a few things that change when you move from renting to owning.
Your Insurance Needs Change
When you rent, your landlord generally carries insurance on the building itself. Your renters insurance is primarily there to help protect your personal belongings and provide certain liability coverage.
When you own a home, you’re responsible for insuring the home itself along with your personal property and liability.
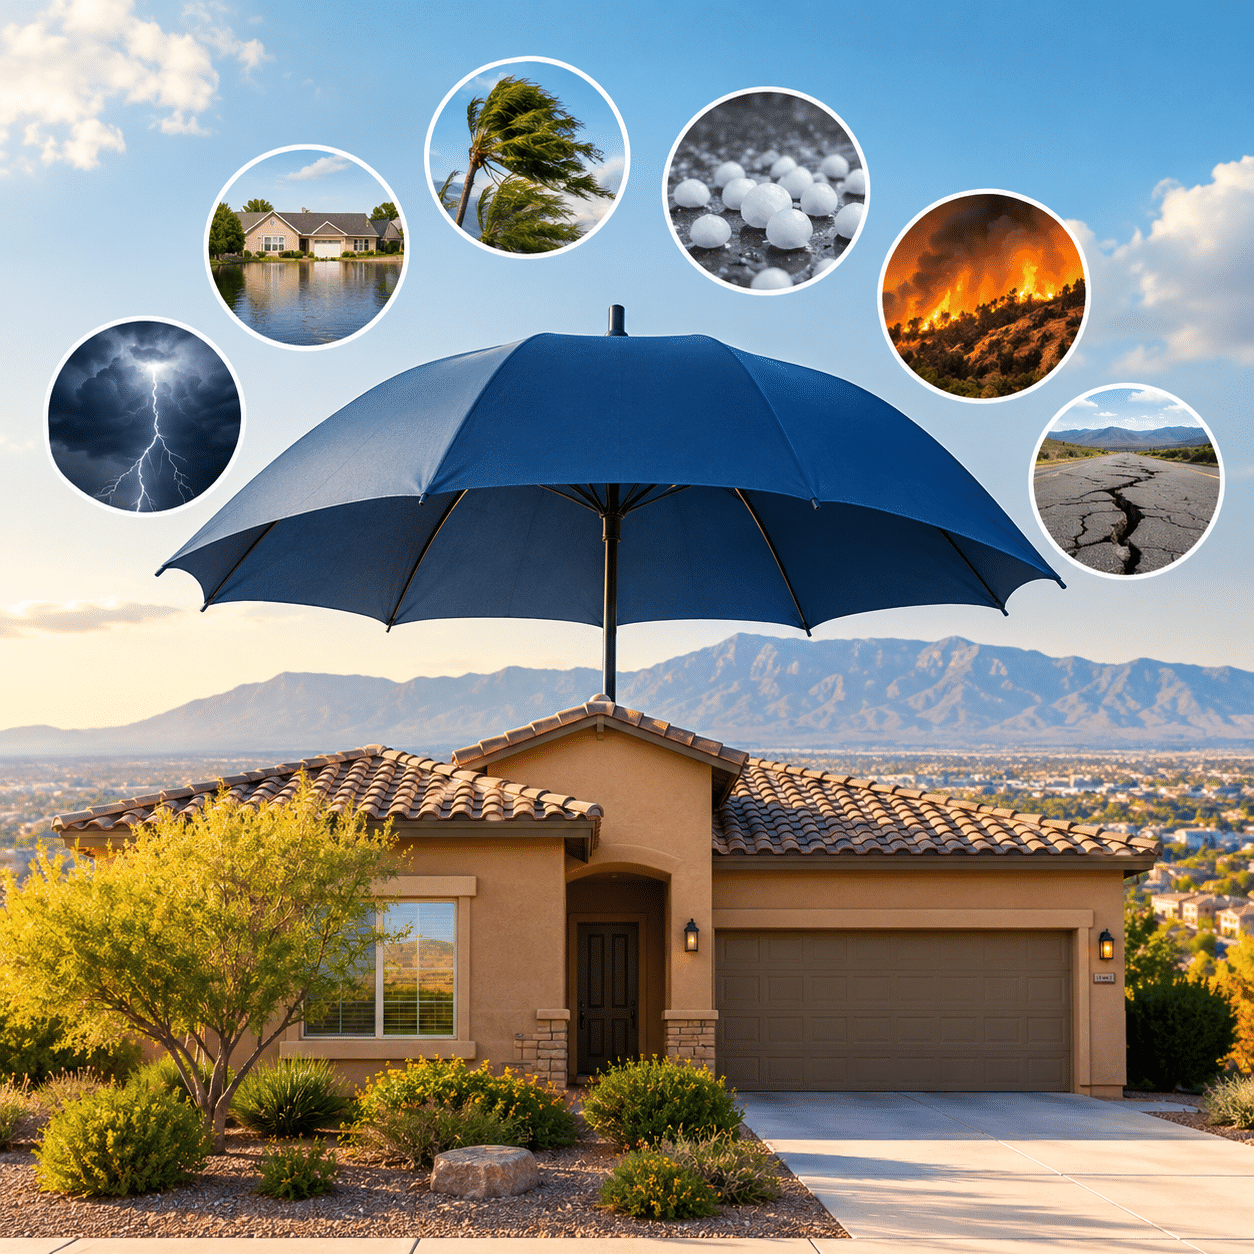
Your homeowners policy can provide coverage for things such as:
- The structure of your home
- Your personal belongings
- Certain other structures on your property
- Personal liability
- Additional living expenses in certain covered situations
The exact coverage depends on your individual policy, so it’s important to understand what you’re purchasing.
Your Lender Will Likely Require Insurance
If you’re financing your new home with a mortgage, your lender will generally require you to maintain homeowners insurance.
That means getting your insurance lined up is often part of the home-buying process before you can officially close.
It’s a good idea to start talking with an insurance agent early rather than waiting until the last minute.
The Price of Your Home Isn’t the Same as the Cost to Insure It
One thing that can surprise first-time homeowners is that the amount you paid for your home isn’t necessarily the amount used to determine the dwelling coverage.
Your home’s market value includes factors such as the land and what buyers are willing to pay in your area. Insurance coverage for the structure is generally based on the estimated cost to repair or rebuild it after a covered loss.
There are a lot of factors that can affect that calculation, including the home’s size, construction and features.
You’ll Have a Deductible
A deductible is the amount you’re responsible for paying toward a covered claim before your insurance coverage applies.
For example, if you have a $2,000 deductible and a covered loss results in $10,000 of covered damage, you would generally be responsible for the first $2,000, subject to the terms of your policy.
Knowing your deductible ahead of time can help you understand what you could be responsible for if you ever need to file a claim.
Your Home and Your Policy Can Change Over Time
Buying the house is only the beginning.
As you make improvements, purchase new belongings or make other changes to your home, your insurance needs may change too.
A new addition, remodeled kitchen, finished garage or expensive new purchase may be worth discussing with your insurance agent.
Regularly reviewing your coverage can help make sure your policy still reflects your situation.
Don’t Forget About Your Personal Belongings
You’ve spent years filling your home with furniture, electronics, clothing, appliances and other belongings.
Your homeowners insurance can provide coverage for personal property, subject to your policy’s terms, limits and exclusions.
It’s also a good idea to keep an inventory of your belongings. Photos, receipts and other documentation can be helpful if you ever need to make a claim.
Your First Home Doesn’t Have to Feel Complicated
There is a lot to learn when you become a homeowner, and insurance is just one piece of the puzzle.
The important thing is to understand your coverage before you need it.
If you’re buying your first home, moving into a new house or simply want to see what homeowners insurance could look like for your property, ABQ Insurance is here to help.
Ready for a Homeowners Insurance Quote?
Give us a call and we’ll help you explore your coverage options.
Albuquerque Office: 505-217-2100
Rio Rancho Office: 505-433-6990
Call ABQ Insurance today for a quote!